 ultimate-guide
Comprehensive Workers Compensation Policy Guide
Table of Contents
- What Workers' Compensation Insurance Covers
- Understanding Workers' Compensation Policy Sections
- Employer Responsibilities and Compliance Requirements
- Workplace Injury Reporting Requirements and Timeline
- How the Workers' Compensation Claims Process Works
- Workers' Compensation Premium Calculation and Cost Control
- Employee Rights and Responsibilities Under Workers' Compensation
- Setting Up Your Workers' Compensation Coverage: A Practical Checklist
- Frequently Asked Questions
Last Updated: October 13, 2026
What Workers' Compensation Insurance Covers
A workers compensation policy provides medical benefits and wage replacement to employees injured during employment. At Paluso & Associates Insurance Services, a proud partner of Orr & Associates Insurance Services, we help businesses understand exactly what their workers' compensation policy covers.
The policy covers work-related injuries and occupational illnesses arising out of and in the course of employment, acute injuries like fractures from falls, repetitive strain injuries like carpal tunnel syndrome, and occupational diseases.
Coverage also extends to wage replacement benefits when employees cannot work during recovery, typically replacing a portion of lost wages. Specific amounts and duration depend on your state's regulations and policy provisions.
One critical distinction: workers' compensation is a no-fault system. Employees receive benefits regardless of who caused the injury, provided it occurred during work, protecting workers from proving negligence and employers from costly litigation.
Understanding Workers' Compensation Policy Sections
A comprehensive workers' compensation policy contains key sections defining coverage, exclusions, and employee protections. Understanding them helps ensure adequate coverage and compliance.
Medical Benefits and Wage Replacement
Medical benefits cover all reasonable and necessary treatment for work-related injuries, including emergency room visits, hospitalization, surgery, prescription medications, medical devices, and rehabilitation. Most policies require approved providers, though some states allow workers to choose their own physicians.
Wage replacement benefits compensate employees for lost income during recovery, typically replacing 60-70% of average weekly wages, though the exact percentage varies by state law.
The wage replacement section also specifies the waiting period before benefits begin (typically 3-7 days) and the maximum duration, which some states limit while others tie to injury severity.
Disability Classifications and Return-to-Work Provisions
Disabilities are classified into categories determining benefit duration and amounts. Temporary total disability means the worker cannot perform any job duties and receives full wage replacement benefits until returning to work or reaching maximum medical improvement.
Permanent total disability applies when injuries are so severe the worker cannot return to any gainful employment, typically resulting in lifetime or long-term benefits.
Return-to-work provisions outline how employees transition back after injury.
Your policy should specify whether modified duty is required, optional, or unavailable. Some employers use return-to-work programs that transition workers from full disability to full duty, improving recovery and reducing claim costs.
Employer Responsibilities and Compliance Requirements
Employers must maintain workers' compensation coverage as required by state law. Most states mandate coverage for all employees, with limited exceptions for sole proprietors and certain business structures.
Establish clear workplace injury reporting procedures. Employees must know how to report injuries immediately, and supervisors must understand documentation requirements. Prompt reporting is critical, delays can complicate claims and result in benefit denials.
Employers must maintain accurate payroll records and employee classifications. Insurance carriers use this information to calculate premiums and verify coverage amounts.
Comply with workplace safety regulations and maintain records of safety training, incident investigations, and corrective actions. A strong safety culture can reduce claim frequency and lower your experience modifier rating.
Workplace Injury Reporting Requirements and Timeline
Prompt injury reporting is essential for proper claims processing and benefit delivery. Employees must report injuries to their supervisor or designated representative as soon as practical, ideally within 24 hours, triggering the claims process.
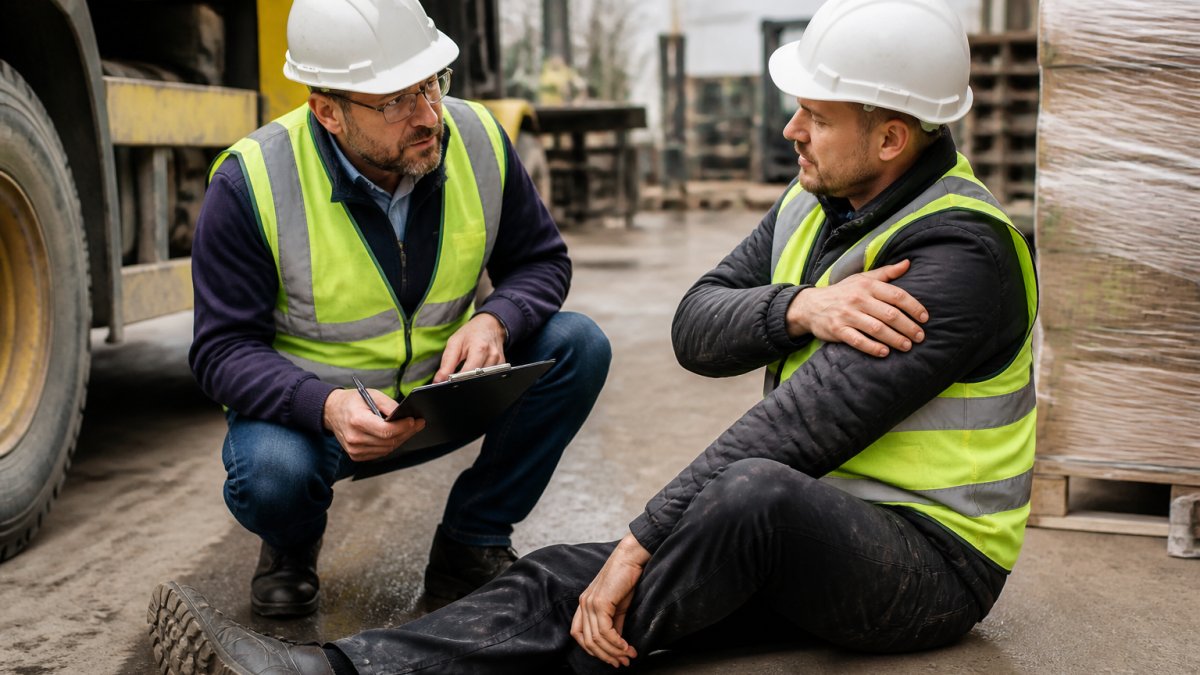
Your company must then report the injury to your carrier within the state-specified timeframe (typically 5-30 days).
Documentation is critical. The supervisor should record the employee's account, witness statements, photos of the scene if relevant, and any equipment or conditions involved, supporting the claim and preventing disputes.
How the Workers' Compensation Claims Process Works
The workers' compensation claims process begins when an employee reports a workplace injury and continues until they return to work or reach maximum medical improvement.
Steps From Injury to Benefit Payment
The workers compensation policy claims process follows a structured sequence. First, the employee receives immediate medical care. The employer documents the incident, what happened, when, where, and who witnessed it, then reports it to the carrier with all relevant documentation.
The carrier assigns a claims adjuster who reviews the report and documentation, determining whether the injury qualifies as work-related under the policy and state law.
Once approved, the employee begins treatment with an authorized provider. The carrier pays medical bills directly and the employee receives wage replacement benefits per the disability classification and state schedule. Medical updates flow between provider, carrier, and employer.
As recovery progresses, the adjuster monitors the case for closure.
Common Claim Denials and Appeals
Claims are sometimes denied. The carrier may determine the injury did not arise out of or occur during work. Pre-existing conditions not aggravated by the job may be denied, as may injuries during unpaid breaks or while violating safety procedures, depending on state law.
Employees have the right to appeal denials, typically by submitting additional evidence, medical documentation, or witness statements supporting the work-related nature of the injury. Many states allow a hearing before a workers' compensation judge if the appeal is denied.
Employers can also appeal certain decisions, such as benefit amounts or treatment authorization. Working with your carrier and understanding the appeal process helps ensure fair resolution.
Workers' Compensation Premium Calculation and Cost Control
Carriers calculate workers' compensation premiums based on several factors. The primary factor is payroll, carriers charge a rate per $100 of payroll for each job classification.
Your experience modifier rating (experience mod or EMR) adjusts base premium based on claim history.
Job classification significantly affects rates, hazardous jobs like roofing or excavation cost more than office positions. Accurate classification is critical for fair premium calculation and proper coverage.
To control premium costs, focus on workplace safety and loss prevention: implement safety training, establish clear procedures, and investigate incidents to prevent recurrence. Document all safety efforts, carriers use this when calculating your experience modifier.
Employee Rights and Responsibilities Under Workers' Compensation
Employees also have the right to know their benefits and how the claims process works. Employers must provide written notice explaining how to report injuries, what benefits are available, and how to appeal a denial.
Employees have corresponding responsibilities: report injuries promptly to their supervisor, follow prescribed treatment and cooperate with rehabilitation, and provide accurate information about how the injury occurred and their symptoms.
Employees cannot receive benefits for injuries sustained while violating safety rules, under the influence of drugs or alcohol, or during illegal activity.
Setting Up Your Workers' Compensation Coverage: A Practical Checklist
Establishing proper workers' compensation coverage requires systematic steps.
| Step | Action | Frequency |
|---|---|---|
| Classify employees | Assign each position to correct job classification for premium calculation | Annually |
| Calculate payroll | Estimate annual payroll for each classification | Annually |
| Obtain quotes | Request proposals from multiple insurance carriers | Annually |
| Review policy | Confirm coverage amounts, exclusions, and endorsements | Upon purchase |
| Establish reporting procedures | Create clear injury reporting process and train supervisors | Upon setup |
| Document safety practices | Implement safety programs and maintain training records | Ongoing |
| Monitor compliance | Verify coverage remains active and payroll is accurately reported | Continuously |
Begin by classifying all employees into appropriate job classifications. Your carrier provides classification codes based on job duties.
Next, estimate annual payroll for each classification, the basis for premium calculation.
Obtain quotes from multiple carriers. Working with an experienced broker like Paluso & Associates Insurance Services, a proud partner of Orr & Associates Insurance Services, ensures you understand policy terms and receive competitive pricing.
Once coverage is selected, establish clear internal injury reporting procedures.
Maintain accurate payroll records year-round. Your carrier audits these at renewal, and discrepancies can trigger premium adjustments.
Finally, monitor your policy to ensure it remains active and your coverage is adequate. According to OSHA guidance on workplace safety, maintaining comprehensive safety documentation supports both injury prevention and proper claims management.
The complexity of workers' compensation, coverage requirements, claims procedures, premium calculations, makes professional guidance invaluable.
Workers' compensation protects your employees when injuries happen and protects your business from liability exposure.
Frequently Asked Questions
What does a workers' compensation insurance policy cover?
Workers' compensation covers medical expenses, rehabilitation costs, and wage replacement for employees injured during work. Coverage includes emergency care, ongoing treatment, prescription medications, and temporary or permanent disability benefits. The no-fault system means benefits are provided regardless of who caused the injury, as long as it occurred during employment and within the scope of the job. Coverage excludes injuries from gross negligence, self-inflicted harm, or violations of safety rules.
How are workers' compensation insurance premiums calculated?
Premiums depend on your industry classification, payroll amount, claims history, and experience modifier rating. Insurance carriers assess risk based on your business type and past claim frequency. Employers with fewer claims receive lower rates through experience modifications. The experience modifier compares your actual losses to expected losses for similar businesses. Payroll size directly affects the premium: higher payroll means higher premiums. Each state sets its own rating system and base rates.
What are the main sections of a workers' compensation policy?
A typical workers' compensation policy includes coverage limits, medical benefit provisions, wage replacement formulas, disability classifications (temporary total, temporary partial, permanent total, permanent partial), exclusions, employee eligibility requirements, and claims procedures. Policies specify maximum benefit amounts, waiting periods before benefits begin, and return-to-work program details. Understanding each section helps employers ensure adequate coverage and employees know what benefits they can expect after an injury.
How does the workers' compensation claims process work?
The process begins with prompt injury reporting to your employer, who notifies the insurance carrier. The carrier investigates the claim, verifies eligibility, and authorizes medical treatment. The injured employee receives medical care while the carrier tracks expenses and wage replacement payments. If the claim is denied, the employee can file an appeal. Most states have specific timelines: employers must report within days, carriers must respond to claims within weeks. The entire process from injury to benefit payment typically takes 1-3 weeks for straightforward claims.
What should an employer do immediately after a workplace injury?
First, ensure the injured employee receives immediate medical attention if needed. Document the incident with details about how it occurred, who witnessed it, and what was the employee doing. Report the injury to your insurance carrier within the required timeframe (usually 24-48 hours). Provide the employee with the required notice of rights and responsibilities. Preserve all evidence and witness statements. Cooperate with the carrier's investigation. Communicate with the employee about their benefits and expected return-to-work timeline.
Can workers' compensation cover independent contractors?
In most states, independent contractors are not covered by the employer's workers' compensation policy. They are responsible for obtaining their own coverage if required by law or contract. However, some states have specific rules requiring coverage for certain contractor types. The classification depends on factors like control over work, method of payment, and whether the person is in business independently. Misclassifying an employee as a contractor can result in penalties, so proper classification is critical.
What happens if an employer doesn't have workers' compensation insurance?
Operating without required workers' compensation insurance exposes employers to serious penalties, including fines, license suspension, and legal liability. If an uninsured employee is injured, the employer may be personally liable for all medical costs and lost wages. Injured employees can sue for damages beyond standard benefits. Most states require workers' compensation insurance for any business with employees, with limited exceptions for sole proprietors. Coverage is mandatory compliance, not optional.
How can employers reduce workers' compensation premiums and claims?
Implement strong workplace safety programs, provide employee training on hazard recognition and safe practices, maintain proper equipment maintenance, and enforce safety protocols consistently. Establish a return-to-work program to help injured employees resume duties sooner. Document all safety efforts and near-miss incidents. Respond quickly to injuries and cooperate fully with investigations. A clean claims history directly lowers your experience modifier and reduces future premiums. Regular safety audits and employee engagement in safety initiatives demonstrate risk management to carriers.